Industry Insights
Money Transfer Made Easy: Secure Compliance Without the Friction
Web-based platforms integrate once with the transfer company, handling KYC capture, multi-layer fraud checks and reporting centrally, not in-store.
Why do money transfer businesses struggle to be both compliant and fast? Because compliance is usually bolted onto the counter instead of built into the platform.
The friction is in the wrong place
Electronic money transfer volumes keep rising, and with them the compliance and fraud burden. Customers accept that anti-fraud checks exist; what they will not accept is being held at the point of sale by long, complicated authorisation procedures. Merchants, meanwhile, cannot absorb an IT project every time regulation changes. Most solutions force a trade-off between the two.
Compliance as infrastructure
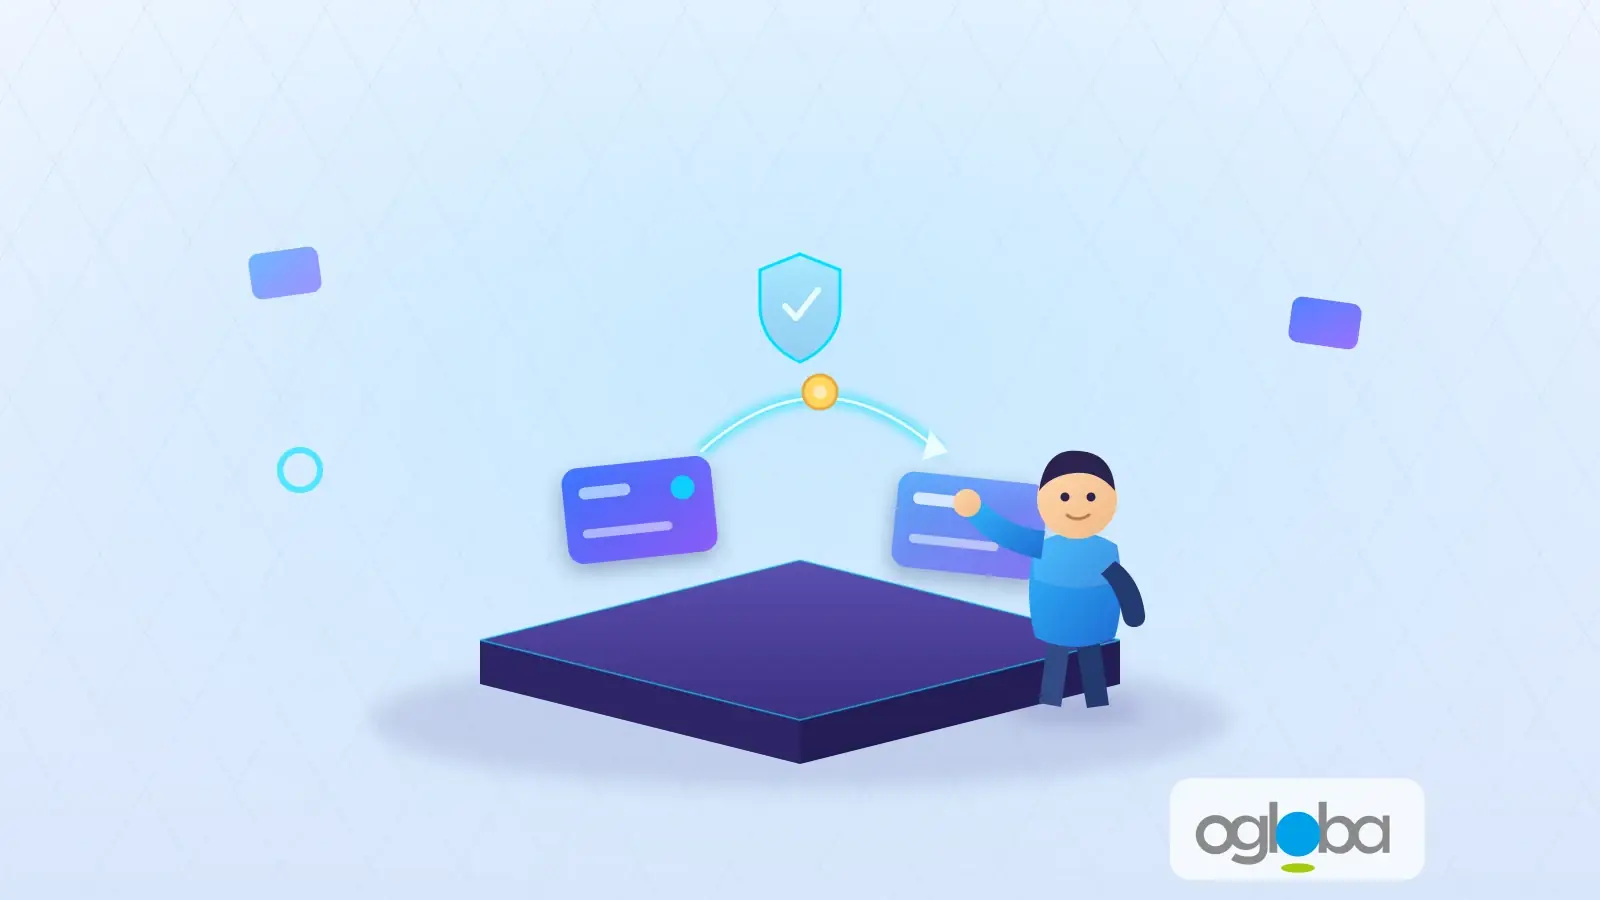
A web-based platform removes the trade-off. Integration happens once, with the money transfer company — not at every merchant point of sale — so there is no development work in store and time to operation stays short. Multi-layer fraud mitigation sits underneath. The front-end interface gathers and cross-checks KYC data in a single flow, while the back office holds the compliance and anti-fraud controls and produces transaction reporting for whoever has to answer for it.
That is the architecture Ogloba built in-house: obligations handled centrally, experience kept simple at the counter. Compliance stops being what slows the transaction down and becomes the reason it can be trusted at speed.
FAQ
Why does a single integration with the money transfer company matter for merchants?
Because the integration happens once, with the money transfer company, rather than at every merchant point of sale. That removes development work in store, keeps time to operation short, and means the merchant does not have to run an IT project of its own in order to start offering transfers.
What sits in the back office of a web-based money transfer platform?
The back office holds the compliance and anti-fraud controls and produces transaction reporting for whoever has to answer for it. Keeping those obligations central, rather than at the counter, is what lets the in-store experience stay simple while the checks still run in full.
Do customers object to anti-fraud checks at the counter?
Customers accept that anti-fraud checks exist. What they will not accept is being held at the point of sale by long, complicated authorisation procedures. The issue is not the control itself but where the friction lands, which is why the checks belong in the platform rather than in the queue.
What happens at the merchant when money transfer regulation changes?
Merchants cannot absorb an IT project every time regulation changes, and on a web-based platform they do not have to. The compliance and anti-fraud obligations are handled centrally, so a change in the rules is dealt with once, at the platform level, instead of becoming a new piece of work at each counter.